

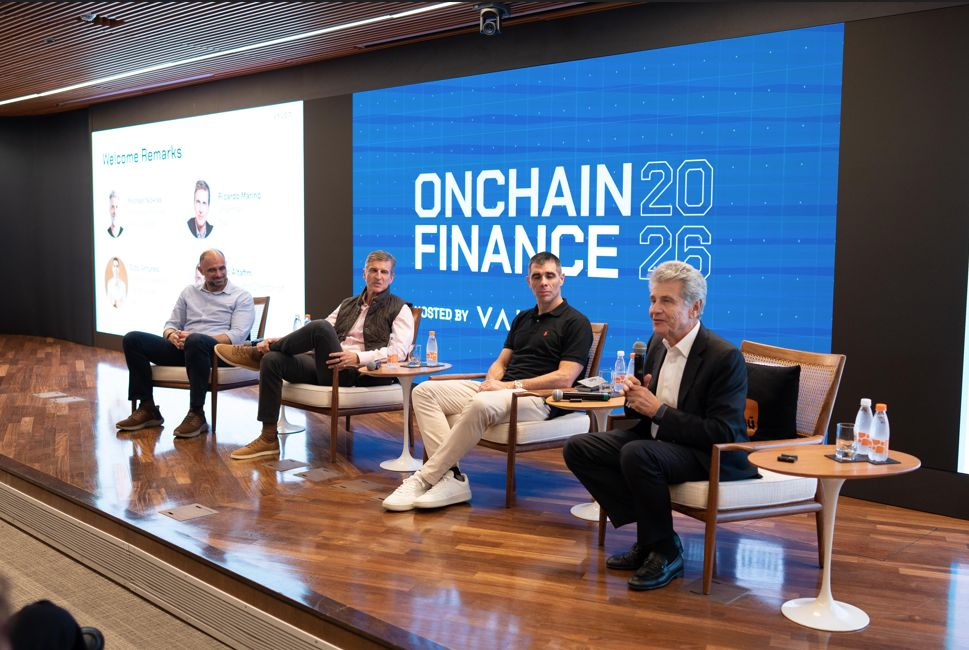
In June, we hosted our first edition of Onchain Finance — four days across São Paulo and Rio, with a room full of people who flew in from 10+ countries to talk about where finance goes onchain.
The conversations cut straight to what’s real: stablecoins moving from crypto-native to institutional rails, real-world assets starting to tokenize, and the custody and settlement infrastructure that regulated capital needs to follow. And it kept coming back to Brazil — a market that isn’t watching this shift from the sidelines, but increasingly building it. We hosted these panels inside the walls of the country’s most prestigious banks, alongside the builders shaping what comes next. When traditional institutions open their doors like this, it tells you where the financial system here is heading.
The panels were sharp, the side conversations were better, and the energy in Rio carried it home. But the thing that made it special was the people — the ones who got on planes, showed up early, stayed late, and leaned in.
Thank you to our partners BTG Pactual, Safra, Itaú BBA, The Linux Foundation, OpenZeppelin, Blockchain.RIO, and the Stellar Development Foundation, and to our sponsors Tether, Sui Foundation, Ondo Finance, Fireblocks, OpenAssets, and Mercado Bitcoin.
Below, a shorter reflection on the market structure taking shape.
Building the Onchain Market Structure
The question is no longer whether blockchain enters finance — it already has, increasingly through institutions rather than around them. The more consequential question is what happens when functions that once lived in separate infrastructures — money, custody, compliance, privacy, settlement, distribution, execution, and autonomous decision-making — begin operating inside the same programmable environment.
At that point, onchain finance is no longer a crypto vertical. It becomes a market-structure problem: whether money, trust, assets, networks, and control systems can be composed into something durable enough for institutions and useful enough for markets. Convergence, though, does not guarantee coherence. A deposit token can preserve bank money while staying trapped in one institution; a stablecoin can move freely while raising reserve questions; a tokenized asset can exist onchain without becoming liquid. The real question is whether these layers can compose without reproducing the old fragmentation in programmable form.
Brazil matters because this is not abstract here. Pix, Open Finance, Drex, stablecoin demand, high local yields, bank-led digital asset infrastructure, and RWA experimentation already collide in the same market — offering a compressed view of the tensions of the next market structure before they are conceptually settled.
Money Becomes a Coordination Layer
The first transformation is not that money becomes digital, but that different forms of money begin to coordinate across systems never designed to move together. Stablecoins make money programmable and portable across institutional and geographic boundaries — behaving less like a balance and more like a coordination layer. The future cash layer will not collapse into one instrument; public money, bank money, tokenized deposits, dollar stablecoins, and local-currency instruments will coexist.
A tokenized deposit preserves the logic of bank money but stays limited in reach. As John Delaney from Crown put it: “a tokenized deposit is a one bank liability.” If one bank issues a digital deposit, another won’t automatically accept it. “You need a layer of liquidity between those tokenized deposits.” That is where stablecoins solve a different problem — connecting systems that would otherwise stay closed. The stronger formulation is not stablecoins versus tokenized deposits, but stablecoins between them.
Brazil makes this concrete. Drex’s more consequential promise was wholesale coordination — deposits, collateral, and balance sheets connected through a regulated settlement logic — but it needs liquidity that moves across institutions and currencies. The Brazilian real carry trade shows the gap: roughly $200 billion in trade still constrained by non-resident account opening, compliance reviews, and FX timing. Dollar stablecoins solved the obvious problem of continuously moving digital dollars, but as they scale, the bottleneck shifts to the local side — reais, local settlement, domestic liquidity. The cash layer of onchain finance will be plural, not pure. It will be coordinated.
Trust Becomes Institutional Infrastructure
If money becomes programmable, trust cannot stay a matter of reputation — it has to become operational. The question is no longer only whether an institution is trusted, but where trust sits in the transaction: how it is specified, monitored, enforced, audited, and recovered. Institutions adopt new systems when their operational uncertainty falls below the alternatives.
Custody is the first threshold — the condition that lets every other activity exist. Without credible custody, an onchain asset may exist technically but remain unusable for collateral, lending, or client distribution. Behind the client’s confidence sit private keys, irreversible transfers, smart-contract risk, and 24/7 markets. Privacy is the second. Wholesale privacy is a market requirement, not retail autonomy — a bank moving a large position cannot expose it to the market, because visibility changes the event being observed. But total opacity fails too; the design problem is enforceable confidentiality — enough privacy for markets, enough visibility for supervisors, enough auditability for institutions.
Compliance completes the layer. KYC, AML, sanctions screening, and supervisory access cannot stay offchain while assets and settlement move onchain — the gap is where institutional risk accumulates. As Chris Brummer from Bluprynt put it: “a market won’t scale unless compliance can scale, and compliance won’t scale unless supervision can scale.” The institutional threshold is not reached when finance becomes faster. It is reached when finance becomes governable.
Assets Become Functional, Not Merely Tokenized
Tokenization’s real test is not whether an asset can be represented onchain — almost anything can — but whether the tokenized form changes what the asset can do: improve distribution, reduce settlement friction, increase collateral utility, or make it composable with lending and treasury infrastructure. A tokenized asset without liquidity or usable collateral pathways is just a digital wrapper around familiar frictions.
Min Lin from Ondo Finance framed it sharply in the RWA discussion: in traditional form, a stock often sits inert inside a brokerage account. The onchain question is whether the tokenized form gives it new utility. The tokenization premium is highest where the asset is most constrained — private credit, private equity, funds, pre-IPO exposure — not where it’s already liquid. As Lin put it: “we’re not changing the performance and structure of asset management; we’re making them more efficient in terms of the rails they access.” Cash comes first, then money market products, then liquid real-world assets, then alternatives.
Brazil is strategically interesting: high-yield instruments, sophisticated capital markets, and a digitally habituated investor base. Brazilian yield, wrapped in a compliant and liquid form, could become more portable than it is today. The domestic path will be incremental — small operational loops rather than grand design.
Networks Become Translation Layers
The network layer is where programmable finance either becomes a market structure or stays a set of disconnected experiments. If every institution tokenizes its own perimeter without a way to recognize others, the result is tokenized fragmentation — the old segmentation of finance in more programmable form.
The problem is clearest in interbank settlement, where message and settlement are still separated and risk sits in the interval between instruction and finality. The promise of onchain infrastructure is that the interval can collapse. The challenge is not choosing one winning chain. Humphrey Valenbreder described Partior’s approach: “leave it to the bank to choose what kind of blockchain, what kind of technology, what kind of L1. And ultimately that’s the pivot that we’re pursuing is to make them all connected. So it’s not a prescription of what technology you need to use.” What matters is the translation layer that lets different forms of money and ledgers interact without collapsing into one universe.
This is where standards become the condition for scale — a shared grammar of who owns what, who can move it, what stays private, and what counts as final. Brazil’s relevance comes from a history of coordinated infrastructure: Pix became powerful because it gave competing institutions a common grammar at the point of payment. The onchain version is harder, but the promise is the same — coherence without homogeneity.
Distribution and Execution Turn Rails Into Markets
Infrastructure becomes real only when it changes how markets are accessed and executed. Exchanges, stablecoin neobanks, trading venues, and wallets are the surfaces through which programmable finance becomes liquid and habitual.
The exchange model is changing — from a venue for token speculation to an account layer where trading, payments, stablecoins, tokenization, and yield converge. Brazil sharpens this: banks have massive customer bases and low acquisition costs; crypto-native platforms have technical agility and cross-border infrastructure. That creates two paths — compete at the interface, or become the infrastructure behind someone else’s. Stablecoin-first neobanks show the consumer side; distribution becomes durable when it stops depending on arbitrage and embeds into local financial behavior.
Execution adds the technical layer — latency, trusted timing, market data, oracles, and liquidity robust enough for institutions. As Rob Sagurton put it in the onchain trading discussion: “one of the biggest challenges with blockchains is figuring out what time an actual transaction came in. And who do you trust?” Markets are built not when rails become theoretically possible, but when institutions rely on them as the normal way to move money, price risk, and execute strategies.
AI Agents Make the Control Layer Mandatory
Agentic finance is where programmability becomes delegated action. Once software can interpret instructions, route transactions, and act on behalf of users, the system has to decide in advance what action is allowed to become real.
The key distinction is between probabilistic reasoning and deterministic execution. AI can interpret and propose, but financial systems require constraints — authorization, spending limits, compliance checks, audit trails. A model can be probabilistic; a payment instruction cannot. Onchain, this is acute because settlement is often final: when an agent acts incorrectly, finality turns speed into exposure, shifting error recovery from an ex-post process to an ex-ante design problem.
The result is a need for bounded agency — defining the corridor within which agents can act: how much they can spend, with whom, what requires human approval, what must be blocked before execution. Agents are not an application layer added after the infrastructure; they are a forcing function that makes the control layer non-optional. Control is not the opposite of autonomy — it is what makes delegated autonomy usable.
Brazil Makes the Stack Visible
This is the deeper reason Brazil matters — not being ahead in every category, but the density with which public rails, regulated banks, capital markets, stablecoin demand, local yield, and new execution infrastructure meet in the same operating environment. Layers usually analyzed separately are beginning to test one another here, which gives the country diagnostic value: it reveals the next coordination problems before they harden into convention.
The next financial architecture will not be built inside a single product, chain, or institution. It will be built at the interfaces: between money and settlement, custody and compliance, privacy and supervision, assets and liquidity, distribution and execution, autonomy and control. What is emerging is not another asset class, but a new operating logic for financial coordination. Brazil is not the answer — it is one of the places where the question is already operational.